Rates Fell for the Fourth Week Straight — Should Houston Bay Area Buyers Jump In Now or Wait?
Mortgage rates just did something they have not done in a while: they fell for the fourth week in a row.
Freddie Mac reported today, November 12, that the average 30-year fixed rate dropped to 7.11% — down from 7.18% last week, and well below the 7.40% peak we saw in mid-October. It is the lowest rate in seven weeks. The 15-year fixed fell even faster, to 6.50%.
So the question I am hearing from buyers all over League City, Friendswood, Clear Lake, Seabrook, and Kemah is a fair one: Is this the moment to jump in — or should I keep waiting?
Here is my honest take.
THE SLIDE, IN ONE LOOK
Mid-October peak — 30-year fixed: 7.40%
Last week: 7.18%
This week — November 12: 7.11%
Source: Freddie Mac, reported November 12, 2026. The 15-year fixed averaged 6.50% this week.
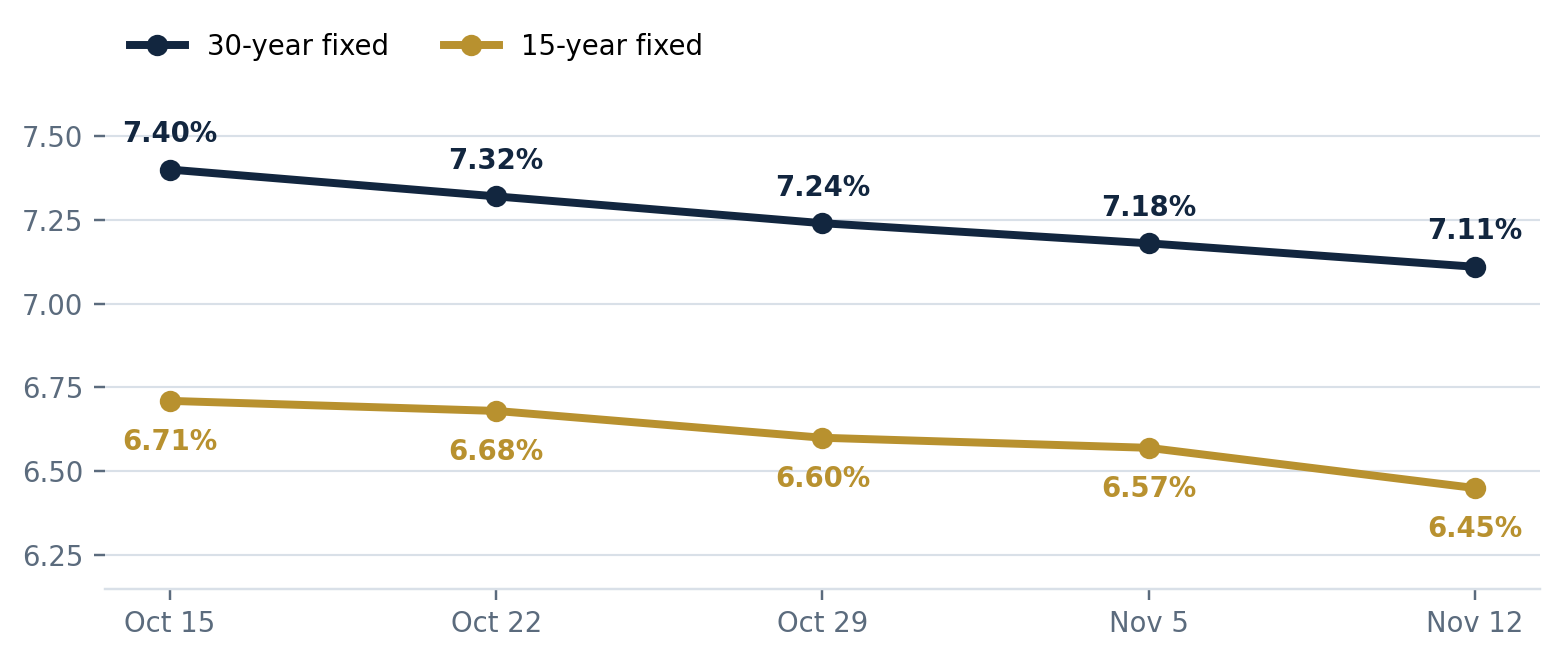 Four straight weekly drops is a trend, not a blip. But 7.11% is a dip, not a plunge — and that distinction matters for your decision.
WHAT THIS DIP IS WORTH IN REAL DOLLARS
Rates are abstract until you turn them into a monthly payment. On a $400,000 loan, principal and interest only:
7.40% — October peak: $2,770/month
7.18% — last week: $2,710/month
7.11% — today: $2,691/month
That is about $79 a month less than at the October peak — roughly $948 a year — for the exact same house and the same loan. It does not transform a budget, but it is real money, and it moves in your favor every week this slide continues.
Payments are principal and interest on a 30-year fixed loan and do not include taxes, insurance, or HOA dues.
SO — JUMP IN, OR WAIT?
The case for moving now:
- You are buying at the lowest rate in seven weeks, after four straight weeks of improvement.
- If you find the right home at a payment that works today, you are not betting on a forecast — you are locking in numbers you already know.
- If rates keep falling after you buy, refinancing is an option. If they rise, you will be glad you did not wait.
The honest case for caution:
- Forecasts for 2027 do not see a big drop coming. If you are waiting for rates in the 5s or low 6s, the outlook does not support planning your life around that.
- A dip can reverse. One strong inflation or jobs report can push rates back up, which is exactly how we got the October peak.
- A lower rate does not fix the wrong house or a stretched budget. The payment has to work at today's rate, not at the rate you hope for later.
For sellers and move-up buyers: a four-week slide is the kind of news that brings sidelined buyers back into showings. If you have been thinking about listing in the Houston Bay Area, improving rates are a tailwind — your buyer pool grows as payments shrink.
MY BOTTOM LINE
Do not try to time the market perfectly — nobody rings a bell at the bottom. If the home is right and the payment works at 7.11%, this is a genuinely better moment than a month ago, and there is no strong forecast saying a much better one is coming.
Want me to run the real numbers on a home you are watching? Call or text me at 979-652-5122, email HomesWithMel@gmail.com, or find me at HomesWithMel.net. I will show you exactly what today's rate does to the payment — no pressure, just the math.
— Melanie Ehrlich, Realtor®, Real Broker, LLC — serving League City, Friendswood, Clear Lake, Seabrook, and Kemah
Recent Posts
Portable Mortgages Explained: How They Work and Why Homeowners Are Paying Attention
What Sets Me Apart as Your League City and Friendswood Realtor: My Value Proposition
Moving to Houston, Texas: What You Need to Know Before You Make the Move
Top Tips for Navigating New Home Construction in Today’s Market
Mastering Work-Life Balance as a Successful Real Estate Agent
Is Now A Good Time To Buy?

The Dos and Don’ts of Receiving Down Payment Gifts from Family & Friends